Block’s Cash App Ushers In Era of Stablecoin Payments, Pivoting from Bitcoin Focus
Key Takeaways
Block's Cash App is fundamentally transforming into a multi-asset payment rail with the integration of USDC, allowing millions of users to spend stablecoins seamlessly like traditional fiat currency.
Table of Contents
Adding USDC to Cash App is a massive pivot for Block. It moves the platform away from its reputation as a purely Bitcoin-centric payment tool and turns it into a multi-asset network capable of handling global stablecoin transactions. Rolling this out to its base of nearly 60 million active U.S. users shows a major shift in strategy. Cash App is clearly responding to mainstream demand for digital currencies that are actually stable enough to use every day.
Historically, Block and its CEO, Jack Dorsey, have been deeply tied to the Bitcoin narrative. Bringing in stablecoins shows a calculated move to diversify and double down on actual payment utility. The setup is straightforward: users can now deposit, withdraw, and pay with USDC directly inside Cash App. This effectively proves that stablecoins aren't just for crypto trading anymore—they're mature, highly liquid tools for daily commerce. The real killer feature here is the ability to instantly convert on-chain USDC into a standard USD Cash balance, cutting out the friction that usually comes with moving crypto into fiat.
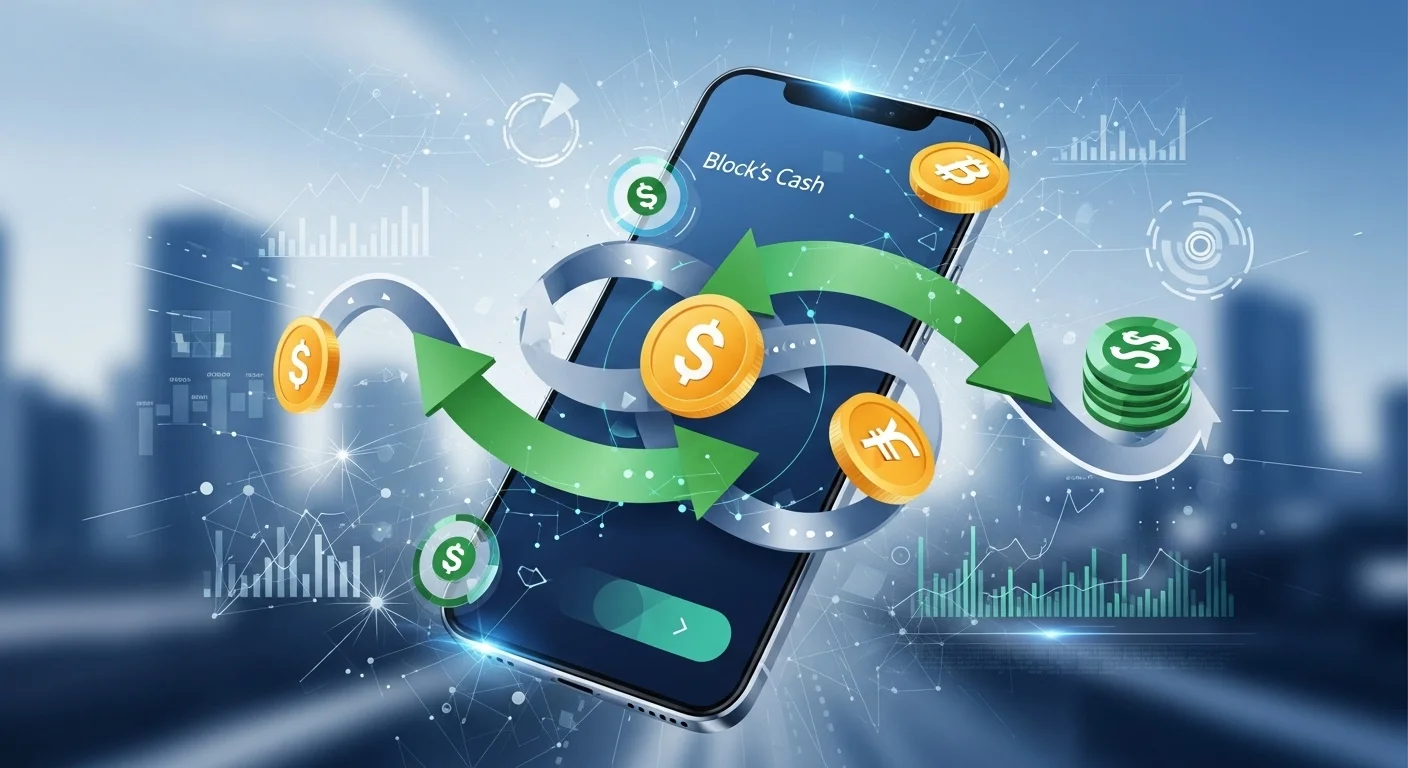
Cash App's shift from Bitcoin to stablecoins
Moving away from a pure Bitcoin focus reflects how global payment infrastructure is maturing. Bitcoin is still the gold standard for decentralized value, but stablecoins like USDC provide the stability needed for everyday retail transactions. By adding USDC, Cash App is boosting its core value: giving people an easy, highly liquid, and stable way to move money digitally. It's a move that helps Block defend its turf in the payments space while capturing a massive growth market in digital asset utility.
Multi-chain tech keeps it seamless
The backbone of this rollout is multi-chain compatibility. Cash App isn't relying on a single blockchain; it supports major networks like Solana, Ethereum, Polygon, and Arbitrum. The initial push heavily highlighted Solana, which makes sense if the goal is rapid, low-cost settlement.
The user experience is built to be simple. Users move funds through standard crypto pathways, and the system handles the complex bridging in the background. It strips away the technical headaches that usually keep regular consumers away from crypto. To the end-user, it just looks like a fast, reliable digital payment.
What this means for the broader payments industry
This launch signals a shift for traditional finance. It proves that stablecoin rails are becoming core infrastructure. Traditional banks and payment networks can no longer afford to treat stable assets and DeFi as external threats; they have to integrate them.
Digital assets are stepping up as practical alternatives to traditional banking, especially for cross-border payments where the time and cost savings are notable. It connects money across borders much more smoothly, bypassing the delays and friction of legacy financial systems.
Google Search Preference
Add Fintech Monster to your preferred sources
Never miss deep, analytical fintech insights. Prioritize our stories in your Google Search, Discover feed, and AI Overviews with one click.
About the Author
Fintech Monster
Fintech Monster is run by a solo editor with over 20 years of experience in the IT industry. A long-time tech blogger and active trader, the editor brings a combination of deep technical expertise and extended trading experience to analyze the latest fintech startups, market moves, and crypto trends.
Related Articles
Recommended
Mastercard Secures BitLicense to Build End-to-End Stablecoin Payments Infrastructure
By securing the NY BitLicense and leveraging partnerships with major crypto platforms and stablecoin issuers like Circle, Mastercard is building a fully compliant, end-to-end payment stack that enables the mainstream spending of digital assets.
SIX and TWINT Solidify Swiss CHF Stablecoin Initiative: A Blueprint for Regulated Digital Payments
SIX and TWINT joining the CHF stablecoin consortium signals Switzerland's deep commitment to establishing a compliant bridge between traditional banking infrastructure and decentralized digital assets.
Inside QNB’s Transformation: How Modular APIs Are Engineering Regulatory Resilience in MENA Banking
QNB's shift to a modular, API-driven architecture allows it to embed advanced compliance and digital services directly into core banking functions, ensuring scalability against evolving regional regulatory mandates.
How Diameter Pay is Rebuilding Cross-Border Payments with Middleware Infrastructure
Diameter Pay secured $10M in Series A funding to build compliant middleware rails, offering B2B clients a real-time alternative to legacy cross-border settlement systems.
The Great Re-Tokenization: Why Tokenized Deposits Are Overtaking Centralized Stablecoins in Institutional Finance
Institutions are increasingly preferring tokenized deposits—which leverage regulated banking rails—over centralized stablecoins due to superior counterparty risk mitigation and inherent regulatory compliance (approaching FDIC parity).