Nvidia Shares Surge Over 4% as Market Cap Exceeds $5 Trillion, Fueling AI Dominance Narrative
Key Takeaways
Nvidia's market capitalization surpassing $5 trillion underscores the immense capital concentration in AI compute hardware, driven by hyperscaler Blackwell and Rubin GPU deployments and silicon photonics interconnect architectures.
Table of Contents
Nvidia shares surged over 4% in heavy institutional trading, propelling the semiconductor titan’s market capitalization past the historic $5 trillion threshold. This milestone firmly establishes the company as the primary tollbooth operator for the global generative AI economy. The aggressive rally reflects unyielding demand from sovereign AI funds, cloud hyperscalers, and quantitative financial institutions racing to secure allocations of next-generation GPU accelerators, specialized interconnects, and turnkey data center compute clusters.
The market’s re-rating of Nvidia is rooted in structural compute scarcity rather than short-term retail momentum. As enterprise generative AI adoption expands from initial experimental pilot projects to full-scale production inference pipelines across healthcare, finance, and industrial automation, computational capacity has transitioned into a strategic sovereign asset. Hyperscalers such as Microsoft, Alphabet, Amazon, and Meta have expanded their capital expenditure commitments, directing hundreds of billions into physical data center builds anchored exclusively by Nvidia hardware architectures.
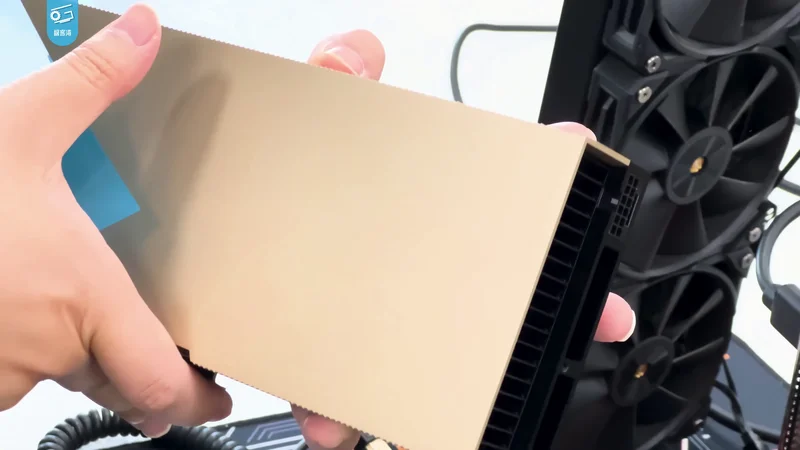
How does Nvidia's hardware and software stack sustain its competitive moat against custom ASIC rivals?
Nvidia’s durable monopoly power stems not merely from raw silicon transistor density, but from its deeply entrenched CUDA software ecosystem and proprietary interconnect architecture. While competing fabless designers and cloud providers develop proprietary ASICs to reduce merchant silicon costs, software developers and AI researchers remain anchored to CUDA’s vast library of optimized mathematical primitives, kernels, and compiler optimizations refined over nearly two decades.
On the physical hardware layer, the rollout of the Blackwell NVL72 and Rubin architectures introduces silicon photonics and 5th-generation NVLink switching technology. By packaging 72 GPUs into a single liquid-cooled, rack-scale computational unit acting as a single monolithic processor with 1.8 TB/s bidirectional bandwidth per GPU, Nvidia achieves orders-of-magnitude lower latency and energy consumption during trillion-parameter model training and Mixture-of-Experts (MoE) inference. This architectural integration creates severe technical switching costs for enterprise customers attempting to assemble multi-vendor accelerator clusters.
Key Facts
- Valuation Milestone: Market capitalization crossed $5.05 trillion, driven by enterprise Blackwell GB200 and Rubin architecture order backlogs.
- Interconnect Dominance: NVLink 5 and Quantum-X800 InfiniBand switches provide up to 1.8 TB/s GPU-to-GPU interconnectivity, outpacing standard PCIe 6.0 standards.
- Software Moat: Over 5.5 million active developers utilize CUDA, creating immense friction for alternative ASIC migration.
What macroeconomic and concentration risks accompany a $5 trillion semiconductor monopoly?
Nvidia’s rapid climb to a $5 trillion valuation introduces unprecedented systemic concentration risk across global equity markets and the broader technological supply chain. The company’s financial trajectory is deeply tethered to Taiwan Semiconductor Manufacturing Company (TSMC) for advanced 3nm/2nm lithography and Chip-on-Wafer-on-Substrate (CoWoS) advanced packaging capacity. Any geopolitical disruption in the Taiwan Strait or critical supply bottlenecks in high-bandwidth memory (HBM4) from SK Hynix or Samsung would immediately choke global AI compute expansion.
Furthermore, Wall Street is scrutinizing the return-on-investment (ROI) timeline for enterprise AI deployments. As hyperscalers amortize billions in annual GPU depreciation cycles, software companies and enterprise customers must generate tangible revenue and operational cost savings from generative AI tooling to justify continued hardware procurement cycles. If software monetization fails to scale at the pace of hardware CAPEX, the semiconductor sector could experience severe cyclical inventory digestion.
Expert Commentary
Having traded semiconductor and tech equity cycles through the dot-com boom, the smartphone revolution, and the cloud migration, Nvidia’s ascent past $5 trillion is the most extraordinary concentration of industrial pricing power I have ever witnessed. Comparing this to past bubbles misunderstands the balance sheet reality: unlike dot-com telecom companies laying unlit dark fiber on speculative credit, Nvidia is generating tens of billions in pure, unencumbered quarterly free cash flow with gross margins exceeding 75%.
However, seasoned market operators know that no monopoly remains unchallenged indefinitely. The true long-term threat to Nvidia is not AMD or Intel, but its own largest customers. Microsoft, Google, and Amazon are pouring tens of billions into in-house silicon (Maia, TPU, Trainium) specifically to cap Nvidia’s pricing power on internal inference workloads.
Over the next three to five years, I expect the market to bifurcate. Nvidia will maintain near-total dominance over the frontier training cluster market where maximum interconnect bandwidth is non-negotiable, while custom ASICs will steadily capture a growing share of routine, low-power inference tasks at the edge. Investors holding tech portfolios must actively model hardware depreciation schedules and energy grid constraints as the primary risk variables governing this unprecedented compute supercycle.
Google Search Preference
Add Fintech Monster to your preferred sources
Never miss deep, analytical fintech insights. Prioritize our stories in your Google Search, Discover feed, and AI Overviews with one click.
About the Author
Fintech Monster
Fintech Monster is run by a solo editor with over 20 years of experience in the IT industry. A long-time tech blogger and active trader, the editor brings a combination of deep technical expertise and extended trading experience to analyze the latest fintech startups, market moves, and crypto trends.
Related Articles
Recommended
HSBC Analysts Predict Major Profit Leap for Alibaba Cloud Driven by Indigenous AI Chip Strategy
HSBC Global Research forecasts a 35% margin expansion for Alibaba Cloud, citing the rapid commercial deployment of in-house T-Head XuanTie RISC-V processors and custom AI accelerators across Asian hyperscale data centers.
Veridue's $4M Pre-Seed: How AI is De-Risking Mega-Cap Energy M&A
Veridue leverages AI and structured data to automate complex due diligence for high-CAPEX energy infrastructure deals, solving major bottlenecks in the renewable M&A cycle.
BUUU Group’s Strategic Pivot: How AI Compute Infrastructure is Redefining Startup Growth
BUUU Group’s $60M+ funding and acquisition of Brightray Science Inc. signal a decisive pivot toward becoming a specialized, high-density provider of industrialized AI data center infrastructure across Southeast Asia.
Beyond the Hype Cycle: XDOF's $1.2B Valuation Signals AI Infrastructure Maturity
XDOF's rapid pursuit of a $1.2B valuation highlights the shift in deep tech investment from generalized AI models to specialized, proprietary industrial data infrastructure necessary for real-world robotics automation.
Bridging the Gap: What Does Kinetiq's Hyperliquid L2 Mean for DeFi Spot Trading Latency?
Kinetiq's L2 deployment on Hyperliquid aims to fundamentally resolve the conflict between decentralized transparency and centralized high-frequency trading speed by implementing ZK proofs and off-chain state channels for near-millisecond execution.