The Battle Over Clarity: Why the Garlinghouse-Dimon Clash Defines the Future of Stablecoins
Key Takeaways
The public debate between Ripple CEO Brad Garlinghouse and JPMorgan's Jamie Dimon over the CLARITY Act highlights the high-stakes clash between crypto-native settlement rails and incumbent tier-1 banking cartels.
Table of Contents
The battle for the future of the global financial plumbing has escalated into open ideological and structural warfare. The high-profile clash between Ripple CEO Brad Garlinghouse and JPMorgan Chase CEO Jamie Dimon regarding the proposed CLARITY Act has laid bare the fundamental divide governing the modernization of money. This is not a superficial disagreement over blockchain adoption, but an existential conflict over who controls the clearing, settlement, and reserve management layers of the multi-trillion-dollar global financial system.
At the epicenter of this confrontation is the question of regulatory statutory boundaries and market access. For crypto-native enterprises, the CLARITY Act represents the long-awaited legislative breakthrough required to permanently end the SEC’s "regulation by enforcement" regime, establishing clear statutory definitions that distinguish decentralized commodities from investment contracts. For Wall Street giants like JPMorgan, any legislative framework that grants non-bank issuers direct access to Federal Reserve master accounts or equalizes regulatory treatment between private stablecoins and traditional commercial bank deposits is viewed as a threat to their core deposit franchise and correspondent banking monopolies.
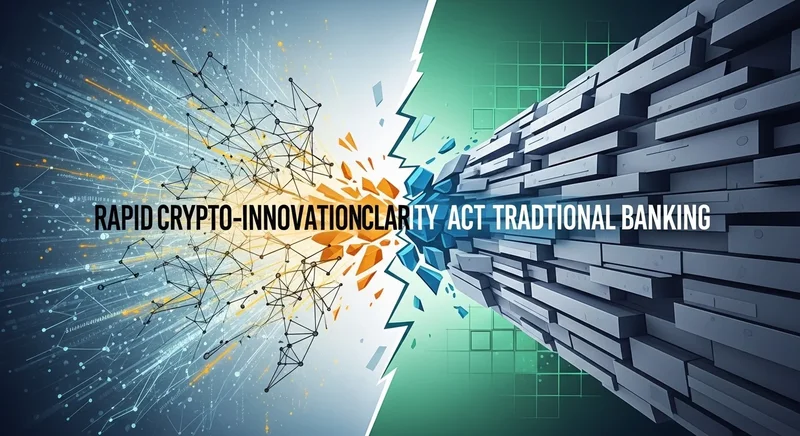
What are the technical and regulatory fault lines dividing Ripple and JPMorgan?
The debate crystallizes around the operational mechanics of real-time wholesale settlement. Ripple’s institutional stablecoin strategy, anchored by its enterprise-grade RLUSD token, operates on public, permissionless distributed ledgers (the XRP Ledger and Ethereum) using cryptographic liquidity bridges to execute atomic, 24/7 cross-border settlements with sub-three-second finality. This architecture completely eliminates the correspondent banking tiers and multi-day settlement delays inherent in legacy SWIFT workflows.
Conversely, JPMorgan’s institutional strategy relies on JPM Coin and the Onyx private permissioned network. This system maintains full compliance within existing Basel III prudential standards and the Federal Reserve's regulatory umbrella, but it operates as a walled garden accessible exclusively to vetted institutional banking clients. Dimon argues that permitting non-bank stablecoin issuers to operate without comprehensive federal bank holding company oversight introduces systemic run risks and circumvents Bank Secrecy Act (BSA) and Anti-Money Laundering (AML) safeguards. Garlinghouse counters that transparent, on-chain reserve attestations and programmatic compliance controls provide superior transparency compared to fractional-reserve balance sheets.
Key Facts
- Legislative Core: The CLARITY Act aims to formally define regulatory boundaries between the SEC and CFTC while establishing federal reserve requirements for non-bank stablecoin issuers.
- Competing Architectures: Public, open-ledger settlement (Ripple's RLUSD on XRPL/Ethereum) versus private, permissioned bank-led networks (JPMorgan's Onyx/JPM Coin).
- Systemic Stakes: Control over the $150+ trillion annual cross-border corporate payments market and the preservation of commercial bank deposit bases.
How will this legislative resolution reshape global liquidity and correspondent banking?
The outcome of the CLARITY Act debate will dictate the velocity and cost of global capital flows for decades. If the legislation passes with robust provisions enabling non-bank issuers to hold high-quality liquid assets (HQLA) directly at central banks, it will trigger an unprecedented wave of corporate treasury migration. Multinationals will no longer be forced to trap billions in idle foreign currency accounts across international banking subsidiaries when they can settle global payroll, supplier invoices, and liquidity swaps instantly via compliant, interest-bearing stablecoins.
Furthermore, this legislative clarity will force global tier-1 banks to adapt or face structural disintermediation. The lucrative fee structures generated from foreign exchange markups, wire transfers, and correspondent clearing fees will rapidly compress toward zero. Banks will be compelled to tokenize their own deposit liabilities on public smart contract networks or partner directly with established digital asset infrastructure providers to maintain transaction volume and client connectivity.
Expert Commentary
Having spent over two decades trading interest rate derivatives and analyzing financial market infrastructure, watching this clash is like watching the transition from open-outcry trading pits to electronic matching engines all over again. The incumbent banking establishment will always defend its moat behind the banner of systemic safety, but the economic reality is that friction, latency, and opaque fees are bad for the global economy.
Jamie Dimon's concerns regarding systemic run risks are valid in the context of under-collateralized algorithmic experiments, but they do not apply to fully backed, 1:1 Treasury-collateralized stablecoins audited in real time on public blockchains. Ripple's aggressive regulatory posture proves that institutional crypto has matured beyond retail speculation into foundational corporate treasury infrastructure.
Looking ahead, I anticipate a hybrid resolution. The CLARITY Act will ultimately pass with stringent capital reserve mandates and continuous on-chain reporting requirements, effectively creating a new class of "Digital Asset Settlement Banks." The institutions that thrive will not be those that lobby to preserve 1970s banking rails, but those that master programmatic liquidity on public, composable ledgers.
Google Search Preference
Add Fintech Monster to your preferred sources
Never miss deep, analytical fintech insights. Prioritize our stories in your Google Search, Discover feed, and AI Overviews with one click.
About the Author
Fintech Monster
Fintech Monster is run by a solo editor with over 20 years of experience in the IT industry. A long-time tech blogger and active trader, the editor brings a combination of deep technical expertise and extended trading experience to analyze the latest fintech startups, market moves, and crypto trends.
Related Articles
Recommended
Gemini Secures Singapore Payments License: De-risking Crypto’s Cross-Border Infrastructure
Gemini's acquisition of a Singapore payment license significantly de-risks its operational footprint in APAC by ensuring compliance with MAS standards, enabling high-volume, institutional-grade cross-border DPT transfers.
CZ’s Kyrgyzstan Visit Unmasks Sovereign Risk in Stablecoin Infrastructure
CZ's recent visit to Kyrgyzstan reveals that even state-backed stablecoin projects like USDKG are fundamentally exposed to international sanctions and regulatory fragmentation, undermining claims of guaranteed exit liquidity.
MiCA's Great Divide: How Europe Set a 'Golden Standard' and Isolated Non-Compliant Digital Assets
MiCA established a globally dominant regulatory framework by mandating rigorous capital controls and auditable reserves for all digital asset issuers, creating immense liquidity pools that are bypassing non-compliant jurisdictions like Poland.
Citi CEO Fraser on Clarity Act: Why TradFi Needs Regulatory Rails for Stablecoin Payments
Citigroup's push for crypto legislation signals that major global banks view regulated stablecoins as the essential "governance layer" needed to move cross-border payments from expensive, slow legacy systems to instant, atomic rails.
Navigating the Ledger Labyrinth: What Banks Must Evaluate Before Adopting Stablecoins for Cross-Border Settlement
Banks must evaluate stablecoins through a tripartite risk framework—operational resilience, jurisdictional compliance (MiCA/Basel implications), and reserve asset transparency—to ensure seamless integration with existing core banking systems like SWIFT.