The Rise of Autonomous Business Entities: How AI and Stablecoins are Building a Self-Sustaining Economic Engine
Key Takeaways
The convergence of autonomous AI agents with programmable stablecoin wallets is enabling the first generation of Autonomous Business Entities (ABEs) capable of executing contractual negotiations, sourcing compute, and managing corporate treasuries without human intervention.
Table of Contents
The global economic architecture is crossing a historic threshold: the emergence of Autonomous Business Entities (ABEs)—fully automated software organizations powered by agentic artificial intelligence and self-sovereign smart contract wallets. Unlike traditional corporate entities that rely on human boards of directors, physical offices, and manual bank signing authorities, ABEs operate as autonomous economic units. They negotiate contracts, procure compute resources, hire freelance human specialists or peer AI agents, and manage corporate balance sheets in real time on decentralized financial rails.
This evolution is the natural synthesis of two breakthrough technologies: Large Action Models (LAMs) capable of autonomous multi-step reasoning, and programmable digital dollars (stablecoins) operating on low-latency blockchain networks. For decades, software automation was constrained to closed API sandboxes because automated scripts could not legally hold a commercial bank account or sign legally binding commercial agreements. By utilizing decentralized smart contracts and compliant cryptographic legal entity wrappers, AI agents can now independently participate in global commerce.
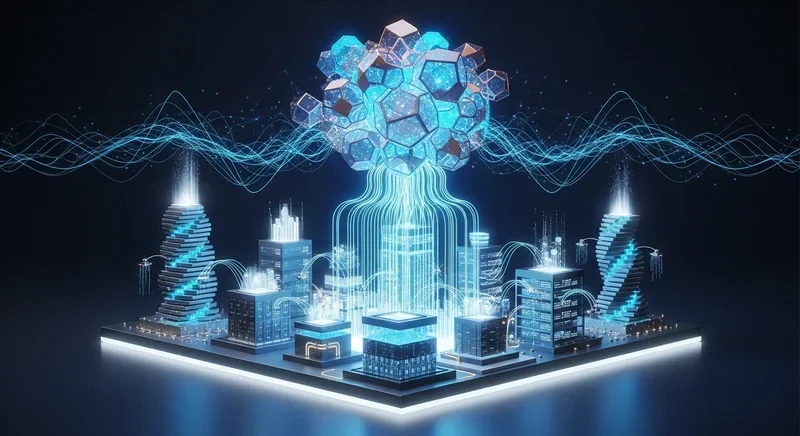
How do Autonomous Business Entities execute commercial contracts and treasury management on-chain?
The operational mechanics of an Autonomous Business Entity rely on a tripartite architecture: an agentic reasoning core, an on-chain multi-signature treasury, and a legal smart contract interface. The reasoning core coordinates specialized sub-agents that continuously scan market demand, pricing APIs, and arbitrage opportunities across global markets.
When an ABE identifies a commercial mandate—such as operating a decentralized data aggregation service or managing a specialized market-making liquidity pool—it deploys programmatic stablecoins (such as USDC or PYUSD) held in its smart contract treasury to procure GPU compute clusters from decentralized cloud networks like Render or Akash. Transactions are executed atomically using Account Abstraction (ERC-4337) smart accounts, allowing the agent to set granular gas budgets, automated session permissions, and conditional escrows that only release payment upon verified cryptographic delivery of services.
Key Facts
- Economic Architecture: Autonomous software organizations combining agentic reasoning with on-chain programmable stablecoin treasury management.
- Execution Rails: ERC-4337 smart accounts and zero-knowledge escrow contracts enabling autonomous Machine-to-Machine (M2M) commerce.
- Legal Innovation: Recognition under statutory decentralized entity frameworks (such as Wyoming DAO/DOA laws) granting automated agents legal personhood and liability wrappers.
What are the legal, regulatory, and systemic implications of machine-to-machine economies?
The rise of autonomous economic actors introduces profound legal and regulatory challenges for global financial authorities. Traditional regulatory frameworks (such as KYC/AML mandates and corporate tax laws) were designed around identifiable human beneficial owners. When two autonomous AI agents negotiate and settle a multi-million-dollar transaction across decentralized liquidity pools, determining legal liability, jurisdictional taxation, and contract breach remedies becomes extraordinarily complex.
In response, progressive legal jurisdictions are pioneering statutory frameworks for Decentralized Autonomous Organizations and Decentralized Organizations (DOAs). These statutes allow AI agent clusters to be wrapped in limited liability company structures, provided they maintain an on-chain, auditable reserve fund and designated algorithmic governance parameters. Furthermore, tax authorities are developing real-time, programmatic micro-taxation protocols that automatically deduct transaction taxes on-chain at the point of smart contract execution.
Expert Commentary
Having spent over twenty years analyzing corporate restructuring, electronic algorithmic trading, and decentralized protocol governance, the emergence of Autonomous Business Entities is the most disruptive economic development since the invention of the joint-stock company in the 17th century. The corporate form exists purely to reduce transaction costs and organize human capital; when software can organize itself, the traditional corporation becomes obsolete for routine digital services.
The economic efficiency of an entity with zero human payroll overhead, zero healthcare liabilities, and instant 24/7 global settlement capabilities is mathematically overwhelming. An ABE can operate on 0.5% profit margins that would bankrupt any traditional human-operated business.
Looking toward the end of this decade, I predict that millions of micro-ABEs will form the foundational service mesh of the global internet economy. They will autonomously manage cloud hosting, route logistical freight, negotiate cross-border supply-chain payments, and arbitrage financial liquidity pools. The investors who understand how to deploy and capitalize these autonomous algorithmic engines will build the dominant conglomerates of the machine age.
Google Search Preference
Add Fintech Monster to your preferred sources
Never miss deep, analytical fintech insights. Prioritize our stories in your Google Search, Discover feed, and AI Overviews with one click.
About the Author
Fintech Monster
Fintech Monster is run by a solo editor with over 20 years of experience in the IT industry. A long-time tech blogger and active trader, the editor brings a combination of deep technical expertise and extended trading experience to analyze the latest fintech startups, market moves, and crypto trends.
Related Articles
Recommended
The AI Custody Dilemma: Why Autonomous Agents Expose DeFi’s Stablecoin Plumbers to Systemic Risk
The integration of autonomous AI agents requiring direct custody of stablecoins like Tether creates a systemic risk vector, where developer oversight failures can lead to unmitigated overspending and potential protocol collapse.
Navigating the Ledger Labyrinth: What Banks Must Evaluate Before Adopting Stablecoins for Cross-Border Settlement
Banks must evaluate stablecoins through a tripartite risk framework—operational resilience, jurisdictional compliance (MiCA/Basel implications), and reserve asset transparency—to ensure seamless integration with existing core banking systems like SWIFT.
Circle’s $400M Acquisition of Tazapay Signals New Era for Cross-Border Payments Infrastructure
Circle's acquisition of Tazapay positions it as a critical bridge between traditional fiat payment systems and decentralized crypto rails, significantly enhancing its regulatory compliance and global B2B reach in an increasingly fragmented financial landscape.
Visa’s Onchain Credit Rail Leap: Is Tokenized Settlement the End of Traditional Banking Clearing?
Visa's integration of onchain credit rails for stablecoin settlement marks a fundamental shift in global payments infrastructure, moving transaction finality from multi-day banking cycles to near-instantaneous blockchain processing.
Why Curve's Soft Liquidation Model Is DeFi's Ultimate Safety Net During Market Drawdowns
Curve Finance's soft liquidation model allows borrowers to gradually deleverage and maintain solvency during severe market drawdowns, providing a critical resilience primitive absent in traditional hard liquidation systems.